Hi there, my friend.
Americans have $19.1 trillion in household debt.
$19.1 trillion!
That’s according to data released Tuesday by the Federal Reserve Bank of New York. It covered the third quarter of 2026 and includes $13.4 trillion in mortgage debt, $1.7 trillion in auto loan debt, $1.7 trillion in student loan debt, $1.3 trillion in credit card debt and more than $1 trillion more in other types of debt.
Every type of debt the New York Fed tracks for the report rose since the last quarter, and there’s little reason to think these debt totals are going to do anything but rise in the next few months.
All of this makes finding ways to improve your financial life more important than ever. And while we spend plenty of time talking about ways to spend less, there’s another side of the equation: making sure you’re earning what you’re worth.
Erin Lowry learned that the hard way. Years ago, over dinner, she found out a friend was getting paid thousands more for the exact same gig.
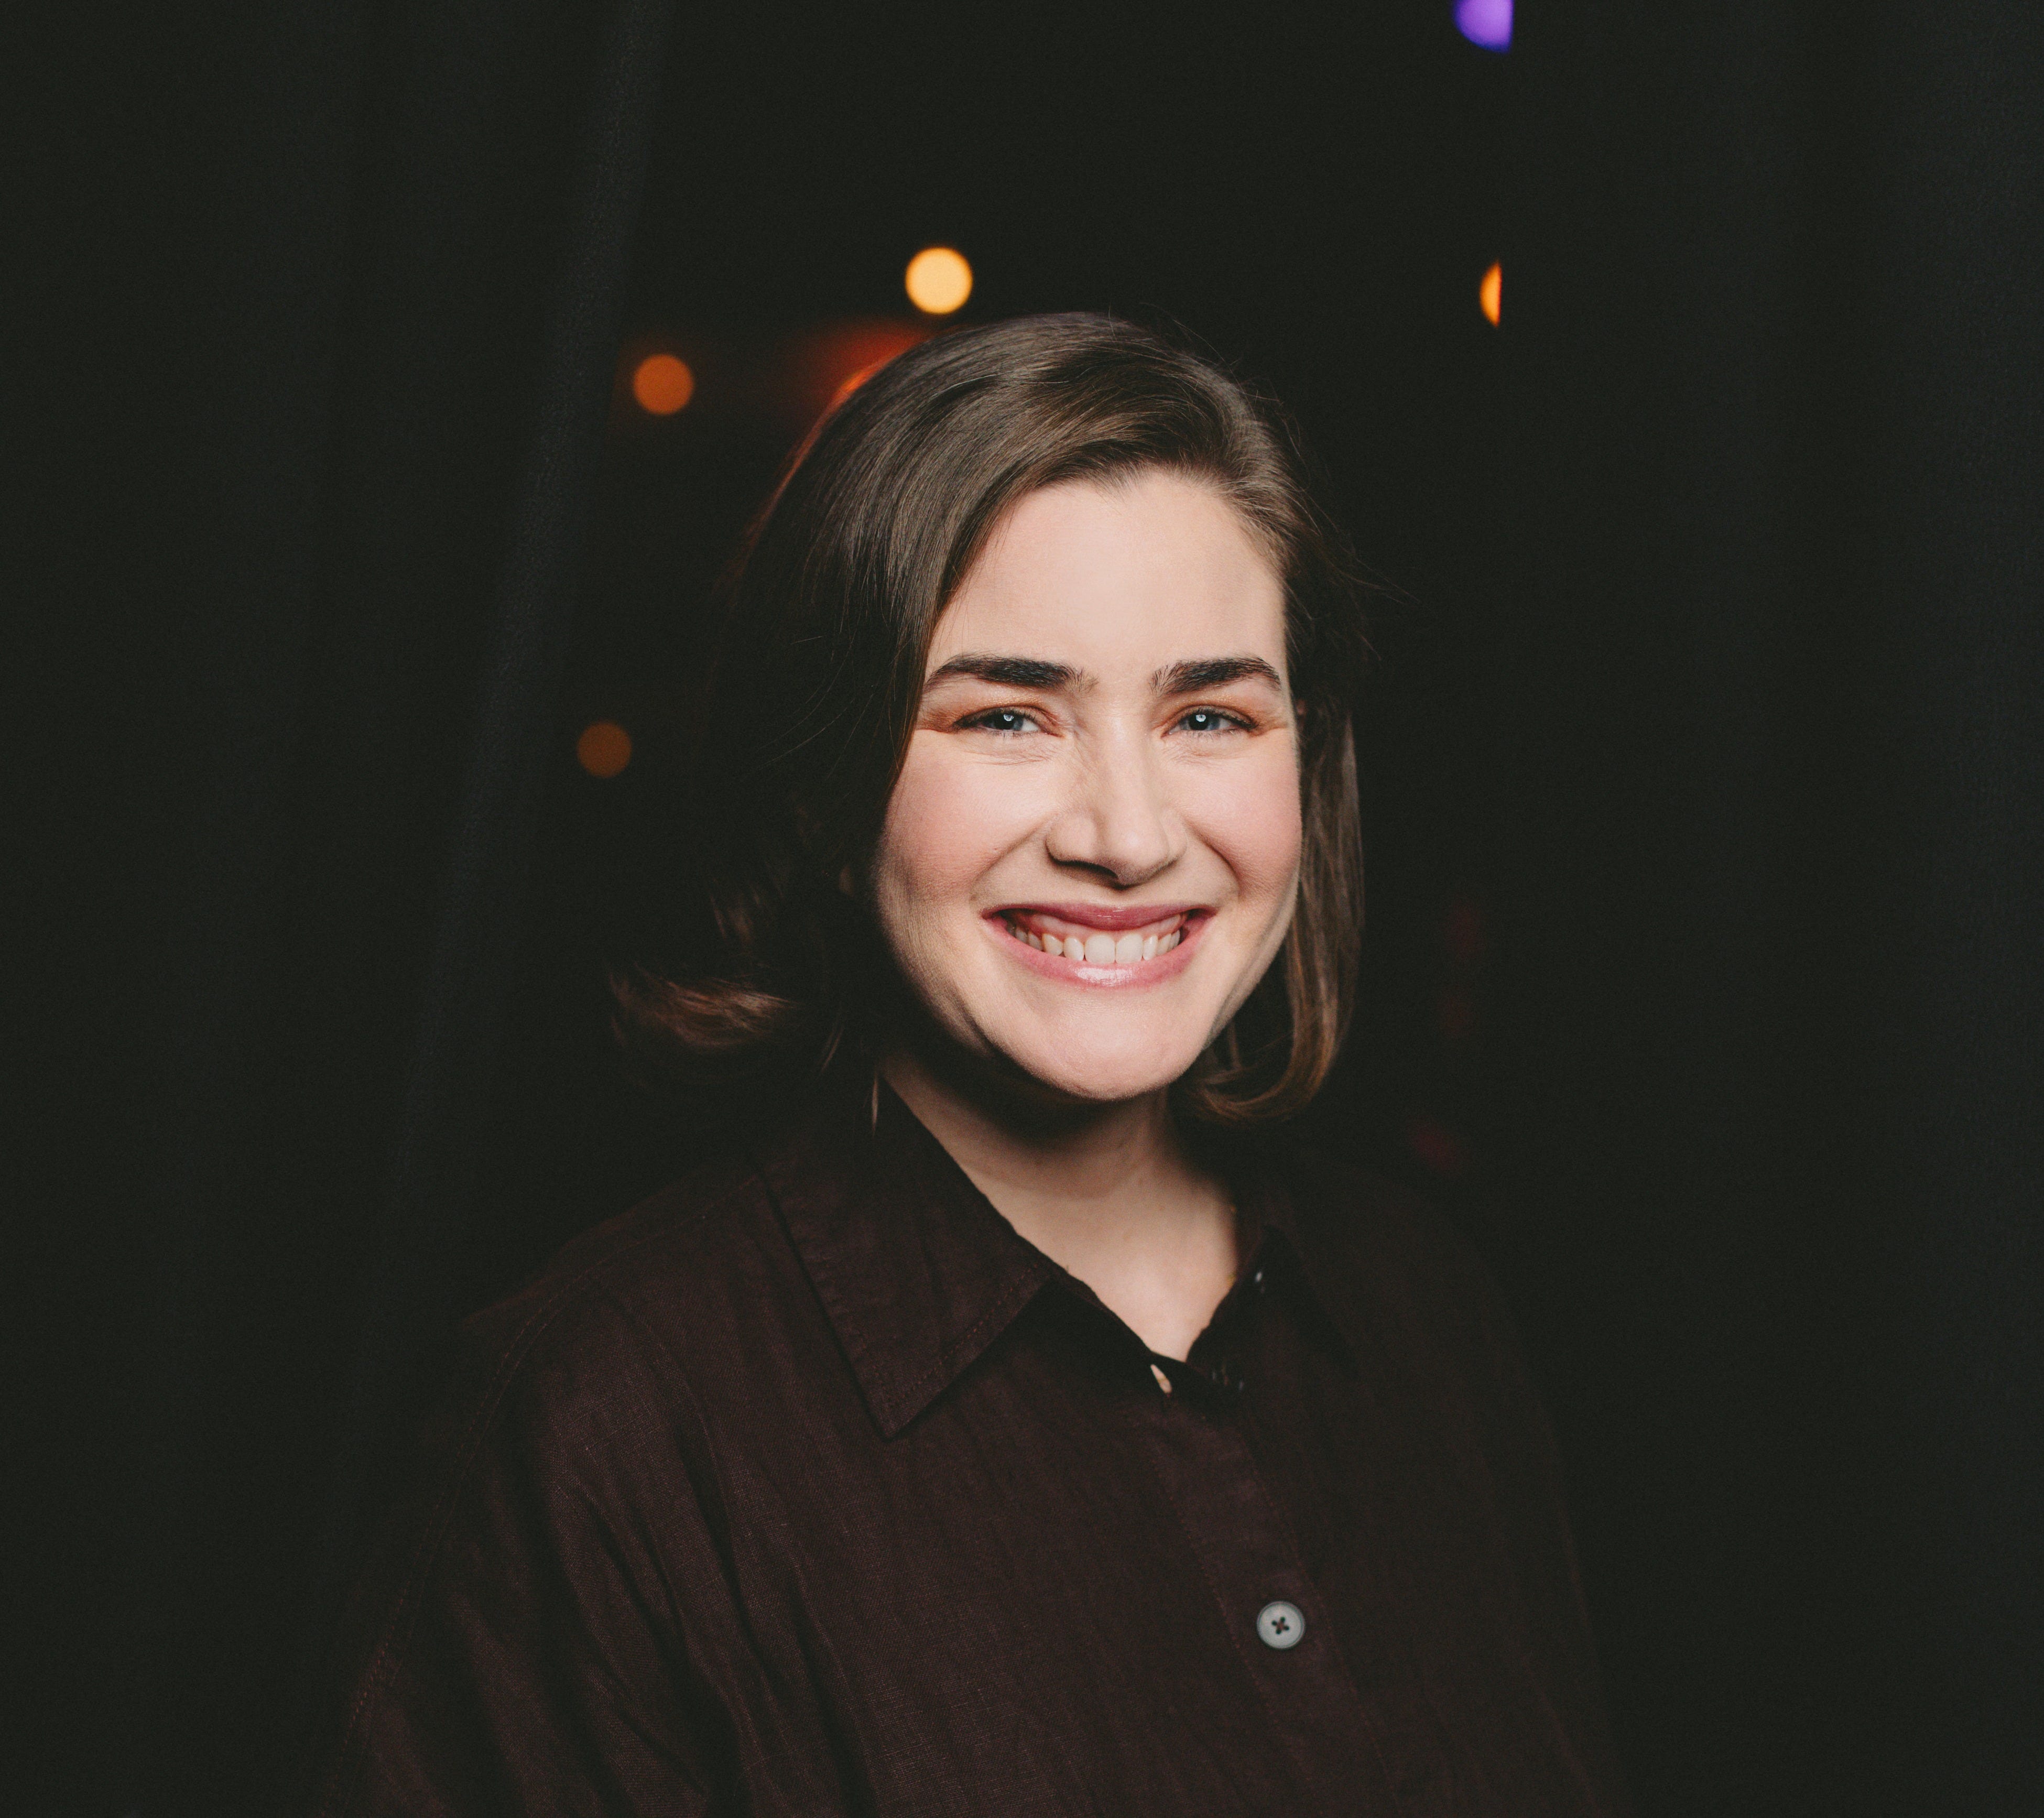
Best known for her Broke Millennial book series, Erin has spent more than a decade helping people navigate the tricky conversations that come with managing money.
Her third book, “Broke Millennial Talks Money: Scripts, Stories, and Advice to Navigate Awkward Financial Conversations,” was a real inspiration for my book: “Ask Questions, Save Money, Make More: How To Take Control Of Your Financial Life.” Seeing Erin’s book, with its focus on scripts and practical, actionable advice, helped give me the confidence to push forward with my own book idea.
She also has a Substack called Hopefully Helpful and even hosts a comedy show about money called Funny Money! (Click the link or scroll down for discount ticket info.)
I recently interviewed Erin about a bunch of money-related topics, which I’ll talk about in multiple posts in the coming weeks. In this post, we touch on the importance of asking for breaks, not just from banks but even from bakeries. She also talks about the conversation that inspired Broke Millennial, as well as a horror story that completely changed how she valued herself as an entrepreneur and what you can learn from it.
Check out the edited transcript below…
Matt Schulz: First, tell me a little about yourself and your Substack.
Erin Lowry: I’m Erin Lowry. You might know me as “Broke Millennial,” aka a financial translator to help you cut through the jargon (and BS) in the finance world. I’ve written three personal finance books (Broke Millennial, Broke Millennial Takes On Investing and Broke Millennial Talks Money) and one workbook (Broke Millennial Workbook: Take Control and Get Your Financial Life Together). I’m a lover of giving unsolicited advice, especially around personal finance.
My newsletter, Hopefully Helpful, is part advice, part reflections, and part personal finance.
Being helpful to someone else is my happy place. Providing guidance or a resource that makes someone’s life easier fills me with joy. It’s hard to know if this compulsion is simply a byproduct of my personality or tied to my birth order (hello, fellow eldest daughters) or being born in the Year of the Snake or being a millennial raised to believe my voice matters, which means I overindex the importance of my opinion and give it far, far too much value.
I also host a comedy show about money called Funny Money. The next show is Nov 15 in NYC, but it's also available virtually. HAHA5 gets $5 off in-person tickets and LOL3 gets $3 off the livestream
MS: Are you naturally comfortable negotiating with people and asking for breaks? If not, how did you become more comfortable with it?
EL: Practice, practice, practice!
Now, I must admit that I’ve been self-employed for a decade. That means multiple clients and partnerships each year, which gives me ample opportunity to practice. Staying at one company for years can make the stakes feel much higher.
But you can always practice in other ways. Call your internet provider and ask for a discount. Call a streaming service or your gym after a price hike and see if you can negotiate back to the original rate. Go into a coffee shop or bakery right before closing and ask if you can get a buy-one, get-one deal on food that’s just going to get tossed at closing time.
If you’re gearing up for a negotiation, then go with the classic roleplay option. Have a friend, parent or partner play the role of your manager and practice making your case for a raise. That way, you won’t be doing it for the first time in the room. Yes, talking into a mirror can help, but speaking to a human is so much better.
MS: What is your best success story when it comes to talking about money? And do you have a horror story to share, too?
EL: Here’s my success story…
In 2012, I was out with a friend who had recently started a new job. A job she absolutely hated. She’d moved to New York to pursue acting and had ended up working as an assistant at an entertainment company and didn’t even have time to audition. I bluntly asked her why she wasn’t willing to take at least a year to get a flexible survival job and pursue her dream. She was young, no kids, not married, no debt, and had parents who could bail her out if needed. She told me she was terrified about money, and the way she handled it was to avoid it and hope she had enough at the end of the month.
That shocked me. It was also the spark for creating Broke Millennial as a blog, which led to the book series and everything I do today.
I’ve always been comfortable talking about money because I was raised in a home where that was normal. It took that conversation for me to realize that I was atypical and that was something of a superpower.
Now, for the horror story…
Years ago, I had my first taste of why it’s so important to ask your colleagues how much they make. I got booked to speak on a panel hosted by a major financial services company. A friend and colleague (in that we were both personal finance writers and speakers) was also on the panel. We were about the same age, with the same experience level and credentials, and even lived in the same city. It was as if all the variables for why she would’ve gotten paid more had been controlled for to teach me a lesson.
We went out to dinner together the night before the panel and, after a cocktail, I worked up the nerve to ask her how much she charged.
The answer stunned me.
She had charged thousands more than I did, which was a lesson for me in what the market could and would bear. It also taught me the importance of asking friends who did similar work what they’d charge for certain opportunities — and to always add 10% to my gut instinct because I was probably undervaluing myself.
MS: What do you actually say when you ask a peer what they charge? So many people never do that simply because they wouldn’t know where to start or are afraid of offending. How exactly should that conversation start?
EL: In this case, I asked her directly what she charged. “I’m not sure if I charged enough for this gig. Would you be comfortable telling me how much you’re getting paid?”
But my favorite strategy is the over/under, which gives people more of an out. “Did you make over or under $[insert sum here]?” Then, if they say over, you can follow up with another over/under or ask, “Do you mind telling me how much over, or give me a ballpark of what you charged/earn?”
MS: Did you raise your rates right after? What happened when you did?
EL: Absolutely! I’ve only been flat-out turned down once for having a high rate. More often, a potential client will say that is out of their range and then counter with what they can afford. It’s then up to me to decide if the work is worth that rate.
MS: Ever regretted adding the 10%?
EL: Nope! It gives me more wiggle room in a negotiation.
Can that be right?
That $19.1 trillion number — the amount of household debt Americans have today — was hard for me to wrap my brain around.
What does that number actually mean?
Check this out…
If you spent $1 million every single day, it would take you more than 52,000 years to spend $19.1 trillion.
Absolute insanity.
Would you go to a “money party?”
A new post from MarketWatch’s Genna Contino — who you might remember from this Ask, Save, Earn post about how she saved $399 on her fiancé's suit just by asking — caught my eye this week. It is about money parties, which she says combine “admin nights, where friends get together to complete tasks they’ve been putting off, with loud budgeting, the concept of declaring your financial limits out loud to your friends and family.”
“And,” she added in the post, “we love an excuse to get together to yap over a few bottles of wine.”
In the post, Genna describes her experience throwing her own money party. She talks about how all involved agreed to make the party a “judgment-free zone” and that everyone would only share as much as they were comfortable with.
She said her biggest surprise was how excited her friends were about the party and how much they were willing to share. I have to say, I think I’d be surprised by that, too. Even though I know that people have gotten far more willing to talk openly about money these days — which is unambiguously a good thing — it still isn’t easy, and there could be massive differences among friends in what they’d be willing to share.
For me, personally, I think I’d feel pretty uncomfortable at a money party. That may seem strange, given that I talk about money all the time and that I’ve even been pretty open about my own mistakes and struggles. Still, there are some topics that I don’t touch on here. Plus, writing about something is far easier for me than talking about something in a roomful of people, even if they’re trusted friends.
I’d love to hear what you think about this idea. Tell me what you think in this poll and in the comments below.
Until next time!
Matt
Thanks for featuring my story!!